


If you run or lead a merit shop contractor in Eastern Pennsylvania, the construction backlog reading that dropped on August 11 should be on your desk right now. Here is what the numbers actually say, where your region fits inside them, and what to do about it before 2027.
You came here because you want a straight answer to three questions: What does construction backlog actually measure? What is the current reading? And is your own work-in-hand healthy relative to it?
A construction backlog is the total dollar value of unearned revenue from signed contracts – work you have been awarded but have not yet completed. Expressed in months, it tells you how long your current contracted work would sustain your firm at its present revenue pace. ABC’s Construction Backlog Indicator is the construction industry’s most widely tracked benchmark for this metric, and it shapes the national construction outlook.
On August 11, 2026, Associated Builders and Contractors reported that the CBI fell to 8.0 months in July, based on a survey fielded July 20 through August 4. That is 0.8 months lower than both June’s reading and July 2025, and the weakest point since January 2026. Many contractors report stable or slightly softer backlogs in 2026, but the direction matters more than the snapshot.
If your firm holds six to nine months of solid, profitable work under contract, you are in decent shape today. But the trendline is slipping, which means now is the moment to re-examine pipeline quality and risk. Stakeholders – lenders, bonding companies, partners – examine backlog health to assess a contractor’s financial stability, and they are paying attention to the same numbers you are.
What follows is not a generic construction industry outlook. It is a practical, Eastern Pennsylvania-specific intelligence briefing.
A healthy backlog helps stabilize cash flow and predicts future revenue. Too little backlog can create cash flow gaps and lead to panic bidding on marginal work. Too much backlog can cause resource overextension and missed deadlines. The sweet spot depends on your firm size, overhead structure, and sector mix.
Here is the formula. Use it internally every month:
(Total backlog dollars ÷ trailing twelve-month revenue) × 12 = backlog in months
Example: A Bucks County merit shop contractor with trailing 12-month revenues of $30 million and $15 million in contracted but unfinished work has ($15M ÷ $30M) × 12 = 6.0 months of backlog. Compare that with the national reading of 8.0 months and the non-data-center average of 7.5 months. That firm is exposed.
Calculate this on the last business day of each month, using consistent methodology so trends are clear over time. Companies increasingly use digital tools to track progress and manage backlog effectively, and even a well-maintained spreadsheet is better than guessing.
Segment your calculation by the slices of the construction market that matter to your firm: commercial construction, industrial, public work in Pennsylvania, data centers and mission-critical, and infrastructure. One blended number obscures where strength and weakness actually live. Add backlog trend data to your monthly leadership dashboard alongside safety metrics, cash position, and margin – and treat it as a leading indicator.
The July CBI at 8.0 months tells a story of two construction markets running at different speeds. ABC Chief Economist Anirban Basu put it plainly: the data center boom masks the depth of weakness elsewhere, and no momentum in any other segment is keeping backlog elevated.
The split is stark. Approximately 12 percent of ABC members with active data center contracts averaged 11.4 months of backlog. The remaining 88 percent – the overwhelming majority of construction contractors nationally – averaged around 7.5 months. The greatest stress appeared among firms in the $30 to $50 million annual revenue category, where backlog fell to its lowest level since March 2020, as fragile supply chains added pressure that can compress backlog and disrupt schedules. Common causes of backlog compression include labor constraints and supply chain disruptions, but right now the dominant factor is that construction demand is concentrating in a narrow band of project types.
In the June reading, the Northeast region contracted sharply and stood more than a month below its year-earlier level, while the South held the longest backlog at 10.3 months. Infrastructure led by sector at 10.1 months, heavy industrial at 9.7, and commercial/institutional at 8.9.
This is a K-shaped construction market. Demand for nonresidential buildings remains steady despite market challenges, but the gains are not distributed evenly. The “headline” 8.0 months is not a meaningful benchmark for your firm unless you know which side of this divide your project portfolios sit on.
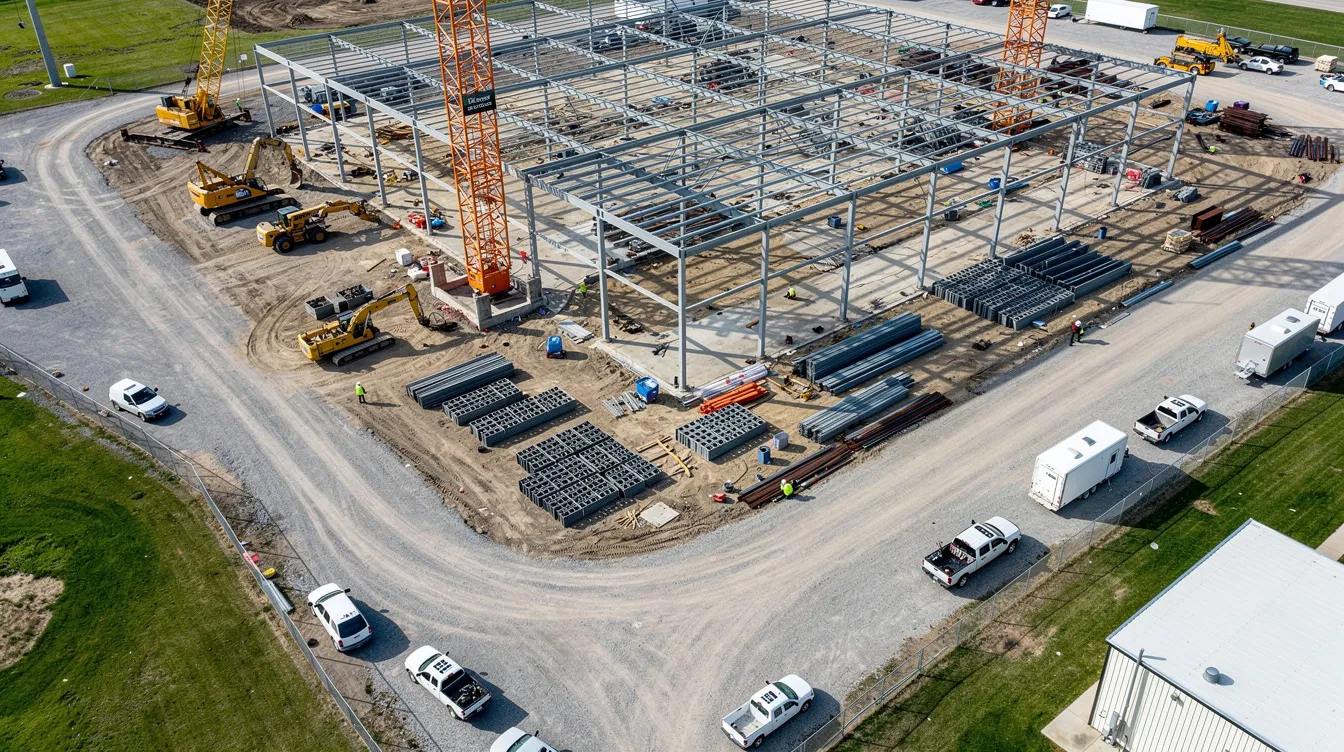
The construction industry in Eastern Pennsylvania is not simply affected by the national data center split – it is physically located at the center of it. The projects inflating the favorable half of the national backlog number are being built inside this region.
Amazon Web Services has committed at least $20 billion over the next decade to two major data center campuses: one in Salem Township, Luzerne County, near the Scranton-Wilkes-Barre corridor, and one in Falls Township, Bucks County, within the Philadelphia metro. Those campuses are expected to generate thousands of temporary construction jobs and over 1,250 permanent positions. In 2025, new data center construction starts surpassed $58 billion nationally, and Pennsylvania is absorbing a meaningful share. Across the state, more than 50 proposed and active data centers are clustered along power and fiber corridors that intersect with ABC Eastern Pennsylvania Chapter territory.
But proximity does not equal access. Large, technically complex data center and energy infrastructure projects carry narrow prequalification lists, heavy safety demands, stringent uptime requirements, and multi-layered owner oversight. General contractors managing these scopes screen on demonstrated mission-critical performance, financial capacity, and workforce depth. A firm in Bucks County that has never performed on a mission-critical facility does not automatically have an advantage over a credentialed firm from out of state.
Qualification, relationships, and proven execution determine which side of the backlog divide a firm lands on. That is the central operational reality for merit shop contractors in this region right now.
Beyond data centers, the broader Eastern Pennsylvania construction market shows selective strength. Construction activity remains stable despite elevated costs and labor constraints, but the activity is shifting in character.
In the Lehigh Valley (Allentown–Bethlehem–Easton), industrial vacancy improved from 9.9 percent to 9.8 percent in Q2 2026 after four consecutive quarters of increases. Roughly 1.3 million square feet is under construction, with approximately half being build-to-suit – meaning a tenant or user committed before the project broke ground.
In the greater Philadelphia region, industrial vacancy moved from 9.7 percent to 9.5 percent. About 5.7 million square feet is under construction, with more than half build-to-suit. Philadelphia County’s vacancy dropped from 12.2 percent to 11.9 percent, driven by large build-to-suit projects, while suburban counties (Montgomery, Bucks, Chester, Delaware) are seeing only a handful of speculative buildings underway – all under 100,000 square feet.
Commercial planning activity increased by 30 percent year over year in August 2025, but much of that has translated into committed, contract-first work rather than speculative pipelines. Along the I-78/81 Corridor, vacancy sits at roughly 7.2 percent, with the Lehigh Valley submarket tighter at approximately 6.0 percent.
The takeaway for construction businesses: the pipeline exists, but it is increasingly spoken for before bid day arrives.
The construction outlook in Eastern Pennsylvania has shifted from a speculative model to a contract-first environment. Build-to-suit dominates. Developers are proceeding when a user is identified, not gambling on speculative leasing.
This rewards contractors who are in the room early – on design-assist shortlists, framework agreements, and negotiated scopes – rather than firms that wait for public bid lists or late-stage hard-bid RFPs. Firms with established relationships and early-stage visibility can smooth their backlog, avoid sudden gaps, and maintain more stable margins.
Construction firms are increasingly adopting modular construction techniques to compress schedules on committed projects, and technology adoption is accelerating across project delivery methods. Cloud-native digital twins are expected to become standard by 2026 on larger industrial and mission-critical scopes, changing how project teams collaborate during preconstruction and execution.
Merit shop contractors in Eastern Pennsylvania should recalibrate business development toward prequalification packages, recurring client touchpoints, and sector-specific pursuit plans targeting data centers, logistics, healthcare, advanced manufacturing, and public infrastructure projects. The firms that position early will capture steady demand; the rest will compete for what is left.
A single “company backlog” number tells you almost nothing useful in a K-shaped construction market. You need at least three views:
Build a simple matrix that shows months of backlog by sector. This surfaces concentration risk. If 70 percent of your backlog is in one sector that is softening, you know it before the revenue cliff arrives.
Review construction industry outlook assumptions for each slice. Stress-test what happens if a major client pauses work. Effective resource allocation involves scheduling labor hours and managing equipment against specific backlog segments, not against a blended average.
Segmenting also reveals where Pennsylvania prevailing wage and prevailing wage compliance obligations are concentrated versus purely private work, which drives different labor cost assumptions. An excessive backlog in a single segment can extend project timelines and strain resources, while thin coverage elsewhere creates vulnerability.
Make this segmented backlog view a standing agenda item in monthly leadership meetings, with estimators, operations, and finance all contributing. Digital transformation is now a competitive necessity in construction, and even basic project management dashboards can automate much of this tracking.
Data center construction spending is projected to grow 17 to 20 percent in 2026, and AI data centers may account for 123 gigawatts of power demand by 2035 – a scale that reshapes the construction sector in any region hosting these facilities. Power demand from US data centers could grow fivefold by 2035, driving surging demand for both the facilities and the energy infrastructure to feed them.
What makes these complex projects different for specialty trade contractors:
Federal incentives and state investment in critical infrastructure are channeling capital into select corridors – often adjacent to high-voltage substations and fiber routes in Eastern Pennsylvania. Cloud computing demand and artificial intelligence workloads continue to drive the pipeline, and this is not a short cycle.
Mid-size merit shop contractors can participate by focusing on niche scopes: concrete, steel, electrical, mechanical, low-voltage, or site and civil packages under larger GCs. But you build that access by compiling a documented record of operational performance, safety, and schedule adherence on smaller mission-critical or industrial projects first. The Amazon campuses in Luzerne and Bucks Counties are multi-year opportunities requiring deliberate positioning now. Waiting for an invitation is not a strategy.
On data centers, energy infrastructure, large industrial campuses, and public work in Pennsylvania, safety performance is a primary gatekeeper for prequalification. Owners and large general contractors commonly request STEP benchmarking data, Experience Modification Rates, OSHA recordables, and evidence of continuous improvement before any trade contractor sets foot on a complex site.
A robust construction safety program includes written policies, field training routines, leading indicators like near-miss reporting and safety observations, and third-party verification. This is not overhead. It is a sales asset.
Prepare a concise safety portfolio with:
Treat your safety program that wins work as a differentiator, not a compliance burden. When a national GC managing a data center campus evaluates trade partners, the safety portfolio often determines who makes the shortlist and who does not. Risk management and risk mitigation on these scopes are non-negotiable, and the bar is rising.
ABC Eastern Pennsylvania Chapter supports members in upgrading safety systems, pursuing STEP recognition, and aligning programs with the expectations of national contractors managing data center and energy infrastructure work in the region.
The construction sector needs 499,000 new workers by 2026, and the industry could lose nearly $124 billion in output due to persistent labor shortages if that gap is not closed. Meanwhile, 41 percent of construction workers are expected to retire by 2031, and only 10 percent of current construction workers are under 25. Only 7 percent of potential job seekers consider construction careers. This is the labor market reality, and it is not improving fast enough.
Construction wages increased 4.2 percent year over year as of August 2025, reflecting pressure from labor availability against rising demand for skilled workers. The aging workforce across electrical, mechanical, and civil crafts is acute in industrial and data center scopes where labor supply is tightest.
Plan craft capacity against the schedule implied by your backlog segments – months of electrical-heavy work on data centers versus months of general building work – rather than simply matching current headcount to open projects.
Construction apprenticeship is the most reliable tool for building durable capacity. A registered apprenticeship in Eastern Pennsylvania provides a structured, earn-while-you-learn path that aligns with both private and public owners’ expectations. Comparable programs elsewhere have demonstrated strong outcomes; ABC Ohio Valley’s apprenticeship programs fill 70 percent of graduate placements. A formal craft training pipeline through ABC Eastern Pennsylvania’s training programs allows you to credibly show large GCs and owners that you can staff multi-year future projects without compromising safety or schedule.
Overcommitting crews to chase thin-margin volume in a tight labor environment is a recipe for cost overruns, rework, and erosion of both profitability and reputation. Workforce development is a backlog strategy, not a separate initiative.
While ABC’s confidence readings for sales and staffing have stayed above the expansion threshold, expectations for profit margins have weakened. Material prices rose 88.2 percent year-over-year in August 2025. Construction input costs increased significantly through 2024 and 2025, with tariffs on steel and aluminum reaching up to 50 percent. Tariff rates for construction goods hit a 40-year high of 25 to 30 percent. Material costs and volatility for construction materials are expected to remain elevated into 2026, and rising material costs are compressing margins even on projects where total construction spending is growing.
In a softening backlog environment – especially outside key sectors like AI data centers and certain energy infrastructure segments – chasing volume with aggressive pricing is how construction businesses get hurt. Prioritizing projects by profitability helps manage the backlog effectively. Incorporate margin thresholds into your backlog analysis:
Public work in Pennsylvania, including Pennsylvania prevailing wage projects, can provide volume stability and infrastructure investment exposure, but carries heightened prevailing wage compliance requirements that must be accurately estimated and managed to protect profit. Elevated costs and elevated interest rates in the broader economy add financing pressure on owners, which ripples into project delays and scope reductions.
AI-driven tools can reduce bid errors by 20 to 30 percent, a lever for protecting margin at the estimating stage. Pair your backlog review with post-job financial reviews, feeding lessons learned from tight-margin jobs into future go/no-go decisions and pricing. Economic uncertainty and trade policy uncertainty make this discipline non-optional.
Start these this quarter to strengthen your position heading into 2027:
ABC Eastern Pennsylvania Chapter is a nonprofit trade association serving more than 500 member companies and over 14,000 merit shop construction employees across Philadelphia, its collar counties, the Lehigh Valley, and Northeast Pennsylvania. The chapter exists to strengthen members – not to sell them something.
Core support areas relevant to backlog management and the current construction market include:
Engage with chapter staff to benchmark your own backlog, discuss sector strategies, and align internal training and safety investments with where the regional construction demand is heading. The Dodge Construction Network, associated general contractors, and labor statistics all confirm that the market is shifting – the question is whether your firm shifts with it.
Monthly updates are the minimum practical cadence for meaningful backlog tracking. Ensure all projects, change orders, and adjustments are current as of the same cut-off date each month. Fast-growing or highly project-driven firms should consider biweekly internal updates to support staffing and purchasing decisions, even if formal reporting stays monthly. Consistency in timing and methodology matters more than perfect precision – the goal is to see trends clearly over time so leadership can act before gaps appear rather than after.
In mid-2026, a backlog of six to ten months is generally considered healthy for established nonresidential construction firms, depending on risk tolerance, capital structure, and mix of work. Firms heavily exposed to cyclical sectors like speculative commercial may want to target the higher end of this range, while firms with stable institutional or public clients can operate safely with somewhat lower backlog. The quality and margin of the work in backlog – not just the months of coverage – should guide whether a contractor’s pipeline is truly healthy. A firm with eight months of low-margin work is more vulnerable than a firm with six months of profitable work.
Start with smaller components of larger campuses – site work, concrete, interior fit-out, or select MEP scopes – under larger GCs already trusted in the data center space. Build a track record on other technically demanding projects (healthcare, labs, advanced manufacturing, residential construction conversions to industrial use) that demonstrate similar safety and quality standards. Use ABC Eastern Pennsylvania Chapter relationships to learn which primes are leading regional data center projects and what specific prequalification criteria they apply to trade partners. The goal is to earn credentials incrementally, not to bid a full campus scope cold.
Pennsylvania prevailing wage work can stabilize revenue and provide multi-year visibility, particularly on projects backed by infrastructure funding, even as private commercial construction cycles. Successfully managing prevailing wage compliance and documentation builds credibility with public owners and GCs, which can translate to invitations for more complex work beyond traditional low-bid environments. Balance your backlog so that prevailing wage projects provide a reliable base while higher-margin private work – data centers, logistics, healthcare – adds upside without overconcentrating risk in any single segment.
Track a small dashboard that includes backlog months by sector, win rate on targeted pursuits, field utilization, safety leading indicators, and gross margin trends on recently closed jobs. Watch regional industrial vacancy and absorption data in markets like Lehigh Valley, Philadelphia, and Northeast Pennsylvania as external signals of future construction activity and construction spending trends. Pair these quantitative indicators with regular conversations with key owners, developers, and lenders to understand how their own outlooks are shifting. Project delays in the broader economy, interest rates, and the labor market all affect whether contracted work converts to revenue on schedule.


